Hims & Hers margin squeeze a year after FDA removed semaglutide from shortage list
The shift from compounded semaglutide to branded GLP-1 drugs cut Hims & Hers' gross margin to 64% from 76%, and average monthly spending per customer rose to $92.
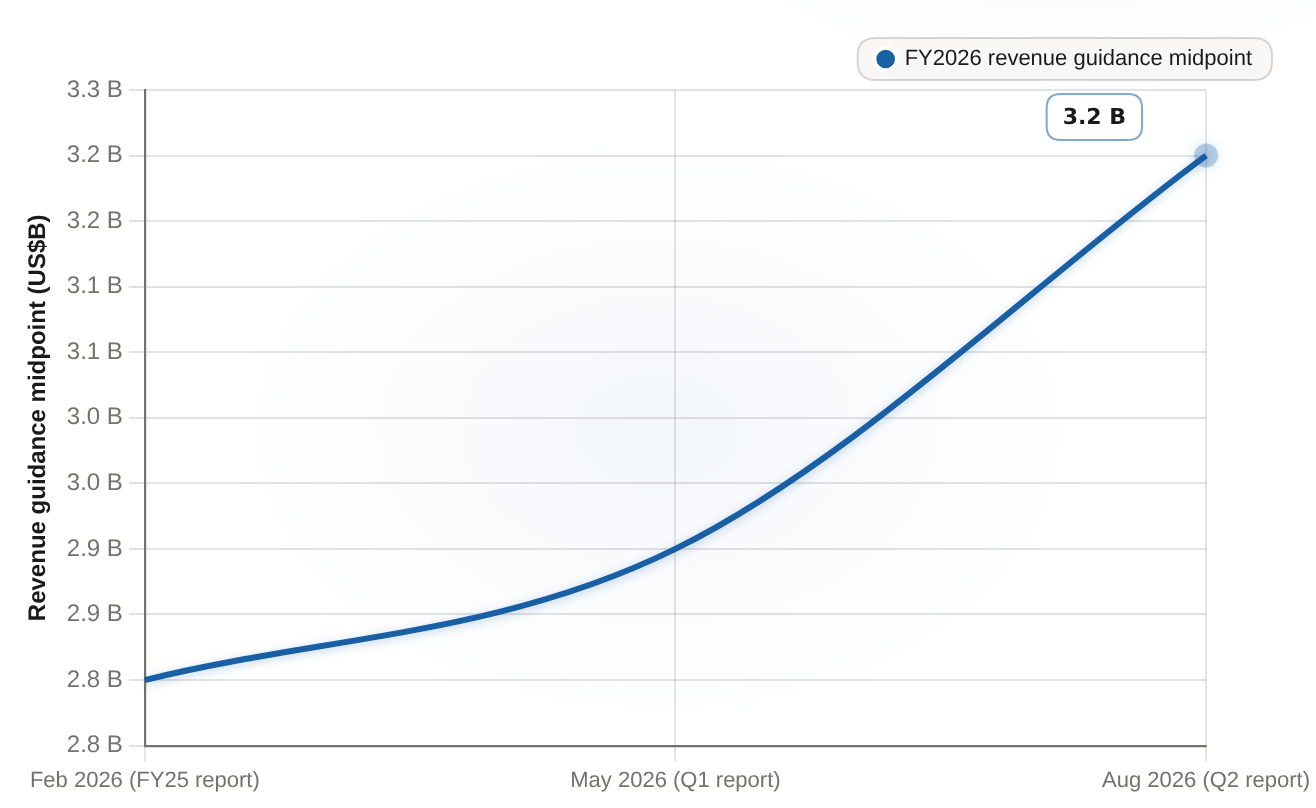
A year after the FDA removed semaglutide from its shortage list, Hims & Hers is still absorbing the cost of moving its weight-loss business from compounded drugs to branded ones. Gross margin fell to 64% in the second quarter of 2026 from 76% a year earlier, and adjusted EBITDA margin dropped to 8% from 15% [1].
Revenue grew 38% to $753.2 million, above the roughly $699 million analysts expected, but the loss was wider than forecast: $0.10 a share on an adjusted basis against a consensus loss of $0.07 [1]. On a GAAP basis, the quarter produced an $86.3 million net loss, compared with a $42.5 million profit a year earlier, and $68.2 million in negative free cash flow [1][2]. Cost of revenue more than doubled to $272 million as branded drug costs ran through the income statement [2]. The company added 300,000 net subscribers, bringing the total to nearly 2.9 million, up 19% [1][2].
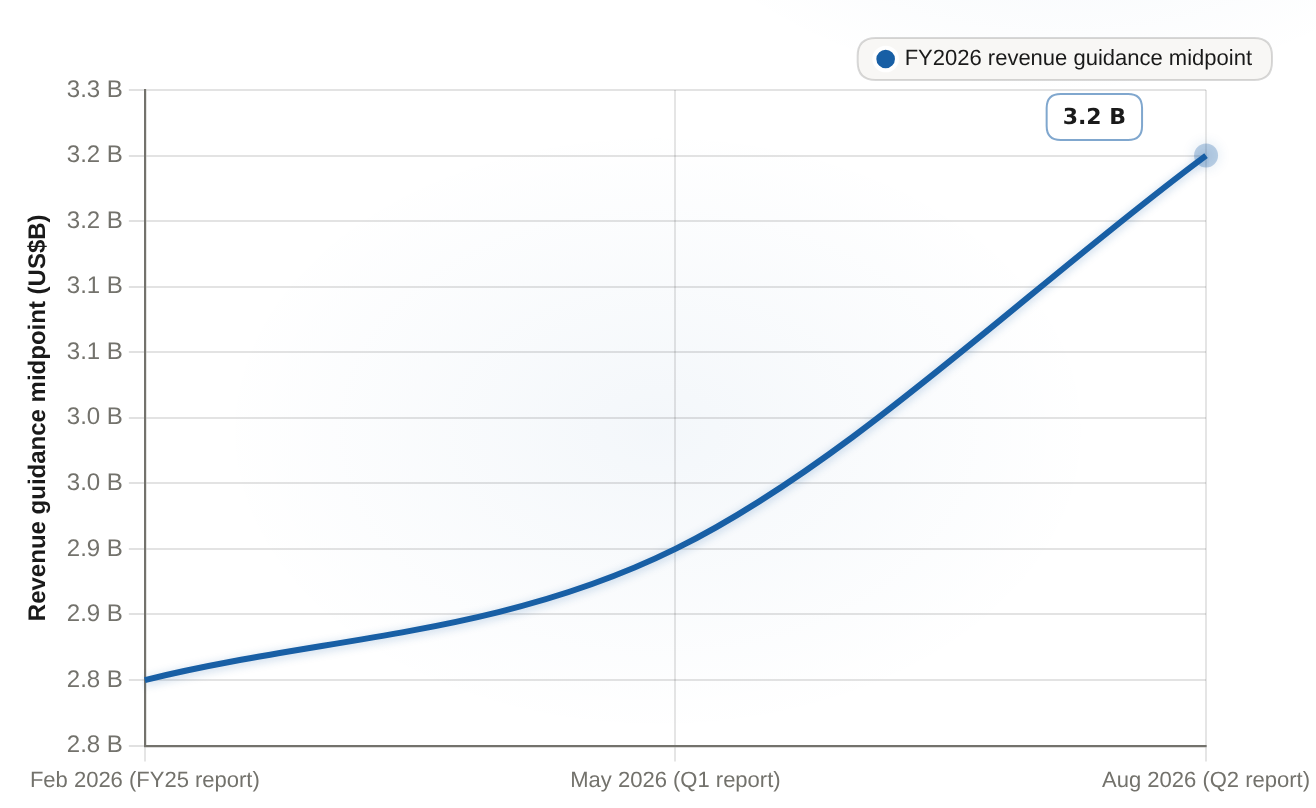
Management raised its full-year 2026 revenue guidance midpoint to $3.2 billion, up from $2.9 billion in May and $2.8 billion at the 2025 full-year report, while cutting the adjusted EBITDA range to $275 million to $325 million from $300 million to $375 million [1]. The company guides to adjusted EBITDA of 9% to 10% of revenue for the year [2].
The margin shift traces to February 2026, when the FDA said the semaglutide shortage was resolved and signaled action against compounders; Novo Nordisk, which owns Ozempic and Wegovy, filed suit [2]. Shares fell as much as 27% in a day and about 50% within weeks [2]. On March 9, Hims & Hers said it would stop advertising compounded GLP-1 drugs, prioritize FDA-approved brands, and resell Novo's Ozempic and Wegovy; Novo dropped the lawsuit [2]. JPMorgan counted more than 125,000 Novo Wegovy shipments in the first six weeks and projects about $1.1 billion in GLP-1 revenue this year, up 46% [2]. U.S. revenue grew 16% in the quarter and 3% over the first half, with part of the rest coming from a 17-fold rise in the rest-of-world segment after the June close of the Eucalyptus acquisition [2]. Average monthly spending per customer rose to $92 from $76 [2].
JPMorgan's Bryan Smilek began coverage of the stock at Neutral with a December 2027 price target of $32, with shares near $25 [2]. A separate analysis put a target near $33, noting the stock trades at about 21 times forward free cash flow [1]. Hims & Hers has said it expects a return to net profitability in 2027 and holds 2030 targets of $6.5 billion in revenue and $1.3 billion in adjusted EBITDA, roughly a 20% margin [1][2]. Chief Financial Officer Yemi Okupe has called the near-term pain "financial noise," and the company took $38 million in first-half restructuring charges tied to writing down its compounding chain [2]. Whether the margin reset was temporary is not settled: one analysis says recovery depends on gross margin holding near 64% rather than eroding toward 60% [1].
Why it matters for patients
The compounded semaglutide channel that made these drugs cheaper for many cash-paying customers has largely closed. Hims & Hers now resells branded Ozempic and Wegovy, which cost more, and average monthly spending per customer rose to $92 from $76 [2]. For people who were buying compounded semaglutide through the company, the product and the price they had access to changed [2]. Subscribers still grew to nearly 2.9 million, up 19%, so the volume of prescriptions moving through telehealth platforms to brand-name GLP-1 drugs keeps rising even as the parent company's profit shrinks [2]. What individual patients now pay out of pocket, and whether lower-cost compounded versions remain available through other sellers, has not been reported in these accounts.
What happens next
The company has said it expects net profitability in 2027, and a full-year 2026 adjusted EBITDA midpoint of roughly $300 million is the bridge to it [1]. Second-half 2026 results will show whether gross margin stays near 64% or drifts toward 60%, and whether full-year EBITDA lands near the middle or the bottom of the $275 million to $325 million range [1]. A first-quarter 2027 report confirming the direction is the next checkpoint cited for a possible move to about $33 a share [1]. The 2030 goals of $6.5 billion in revenue and $1.3 billion in adjusted EBITDA remain the long-range targets [2].
Images from the sources
Sources
Semaglutides.org provides information only, not medical advice. Talk to a licensed provider about your own care before making changes. Some telehealth links are affiliate links and are labeled where they appear.